When debt feels overwhelming, the first priority is not to solve everything in one day. It is to slow the situation down enough that you can see what is urgent, what can wait, and where support is available. Many people avoid opening letters or answering calls because they are frightened of bad news, but getting a clear picture of what you owe is often the first step towards feeling more in control. Debt problems can happen after a job loss, illness, relationship breakdown, rising living costs or simply trying to cover essentials for too long. It does not mean you have failed.
Start by separating your debts into categories. Priority debts are usually the ones that can affect your home, energy supply, council tax, court action or essential services if ignored. Non-priority debts are still important, but they do not usually carry the same immediate risks. This distinction matters because it helps you focus your energy where it will make the biggest difference. If you are struggling to pay rent, mortgage, council tax, gas, electricity or magistrates' court fines, get advice on those first. Protecting basic stability gives you a better chance of dealing with everything else.
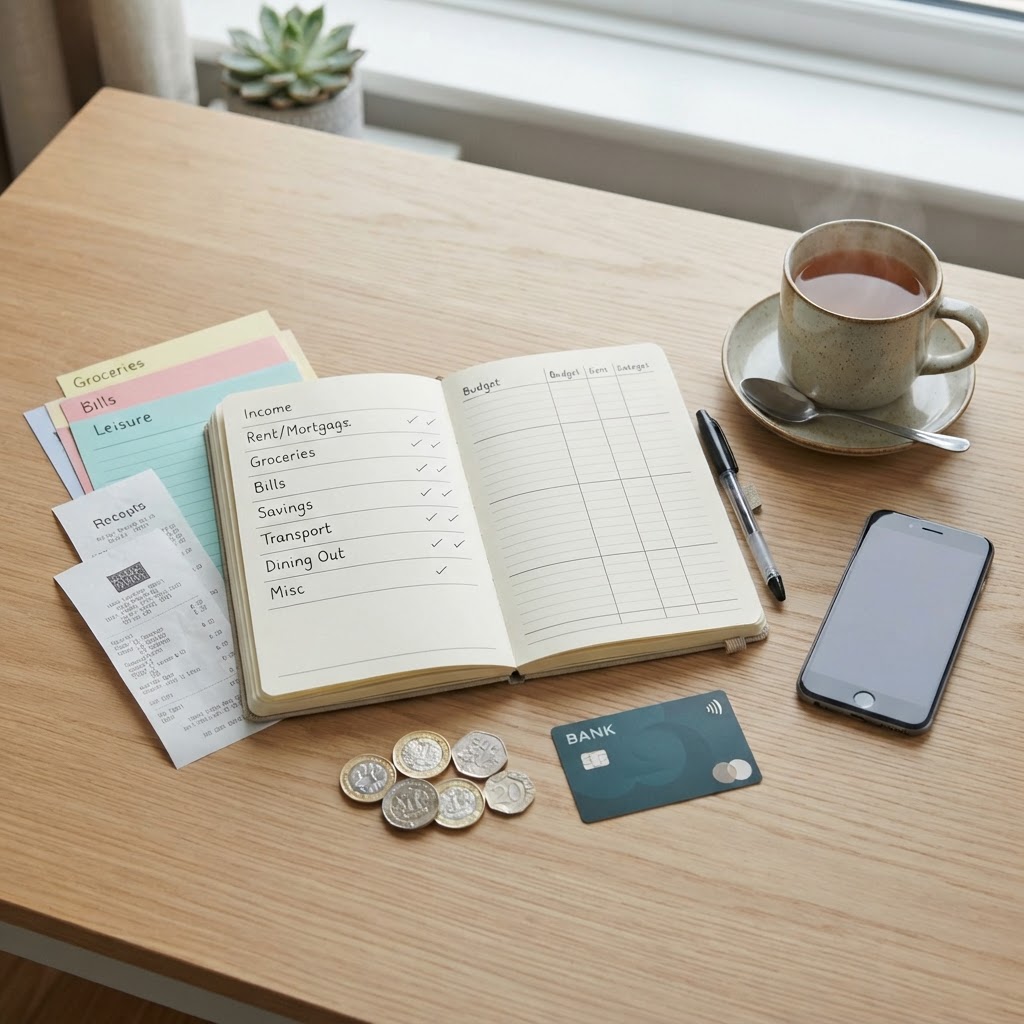
Next, make a simple list of who you owe, how much is owed, and whether payments are already being missed. You do not need a perfect spreadsheet. A notebook page, phone note or printed list is enough. Include income, essential spending and any arrears building up. This helps you understand whether you can realistically offer payments, ask for breathing space, or need debt advice to negotiate on your behalf. If collectors are contacting you, you can tell them you are seeking advice and ask for communication in writing if calls are making things worse.
Free debt advice can make a major difference. A trained adviser can help you check your budget, explain your options, see whether you are missing benefits or discounts, and support you with letters or arrangements. In some cases, there may be formal debt solutions, but often the most helpful first step is simply creating breathing room and reducing pressure. If your debt is affecting your sleep, mood or ability to cope, mention that when you ask for help. Debt is a financial issue, but it can have a real impact on mental health too, and you deserve support with both.